Data cut-off: sales and rentals 1 January–30 June 2026; apartment project rankings 1 January–4 September 2026; infrastructure and developer sources reviewed 4 September 2026 · Evidence reviewed: 4 September 2026
Key takeaways
- Centrality is the starting advantage: District One’s developer lists approximately 8 minutes to Business Bay, 16 to Downtown and 18 to DXB; actual journeys depend on location and traffic.
- A compelling family-living offer: selected communities combine gated access, green space and recreation close to central Dubai.
- Premium housing benchmarks are rising: Meraas’s Nad Al Sheba Gardens Phase 10 launch sheet starts three-bedroom townhouses at AED 5.1 million, providing a relevant benchmark for the wider corridor.
- Connectivity has a substantial next chapter: the approved Gold Line includes Meydan and planned Etihad Rail integration, alongside the awarded Al Meydan Street road programme.
Area at a glance
- DLD geography
- Evidence selection: Meydan, Nad Al Sheba First; not the whole wider Meydan/MBR City marketing area
- Development stage
- Mixed: operating communities plus a substantial pipeline
- Investor category
- Central growth, selective income and luxury
- Residential proposition
- Central apartments, gated family communities and premium villas/townhouses
- Future transport
- Approved Gold Line; planned Etihad Rail integration at Meydan
- Principal access
- Al Khail Road, Dubai–Al Ain Road and Al Meydan Street
- Likely resident
- Professionals, couples, families and premium end users
- Evidence period
- 1 January–30 June 2026
Location and operating context
Meydan’s location is a core part of its appeal: Al Khail Road, Dubai–Al Ain Road and Al Meydan Street connect the corridor with Downtown, Business Bay and the wider city. Nakheel’s District One location guide lists approximately 8 minutes to Business Bay, 16 minutes to Downtown and 18 minutes to Dubai International Airport. These are indicative developer journey times for District One, not a promise of identical access from every Meydan address.
Future rail connectivity: RTA’s approved Gold Line will serve Meydan and integrate with Etihad Rail there. This adds a significant longer-term public-transport dimension to an already central road-connected location. Station access and the opening timetable matter at project level; the planned connection is not an operating Meydan rail service today. See the delivery timeline below.
Central living with a family-community setting
The attraction is the combination of proximity and residential space: access to central employment districts alongside villas, townhouses, landscaped communities and cycling or walking routes. Meraas describes Nad Al Sheba Gardens as a private gated community, while Nakheel specifies gated living and 24/7 security for Naya at District One. These are community-specific propositions, not a uniform security designation for the whole district.
For families, the comparison is therefore about more than price per square foot: privacy, outdoor space, daily commuting and community quality all matter. Check which amenities are operating in the selected phase and test the actual school, shopping and work journeys.
Market composition
Meydan is not one uniform residential market. Branded off-plan towers may target international luxury buyers; value-oriented apartment buildings serve a different tenant and resale pool; and villa communities depend more heavily on family amenities, plot position and community maturity. DLD registration geography also differs from marketing geography, so every comparable set should use the same project, property type, bedroom count, stage and period.
What the H1 2026 evidence shows
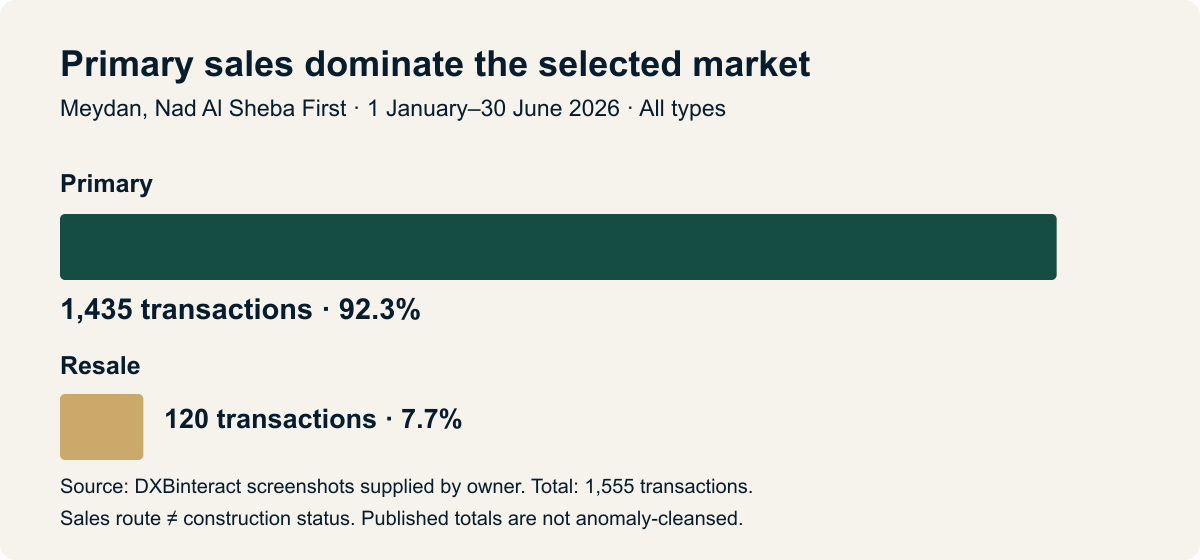
Source: owner-supplied DXBinteract screenshots for “Meydan, Nad Al Sheba First”, Sales, 1 January–30 June 2026. Type is All for the aggregate and Apartment or Villa for the subsets below; Beds and Status show no explicit selection. Hidden “More” settings were not captured. Primary/resale describe the sales route; ready/off-plan describe construction status and cannot be inferred from that route.
| H1 2026 segment | Transactions | Median price (AED) | Median AED/sq ft |
|---|---|---|---|
| All types, all sales routes | 1,555 | 1,412,000 | 3,560 |
| All types, primary | 1,435 | 1,411,000 | 3,590 |
| All types, resale | 120 | 2,512,000 | 1,570 |
| Apartments, primary | 1,399 | 1,408,000 | 3,580 |
| Apartments, resale | 100 | 1,433,000 | 1,510 |
| Villas, primary | 2 | 35,330,000 | 1,800 |
| Villas, resale | 19 | 6,100,000 | 1,720 |
The 1,499 apartment and 21 villa transactions sum to 1,520, leaving 35 transactions in other/unclassified types within the all-type total; these have not been assigned to plots or commercial property without evidence. Two primary-villa transactions are too few for a representative price benchmark. The published aggregates are reproduced as displayed, not cleansed of unusual transactions. Combined transaction value was not supplied.
Custom-range change badges compare against the immediately preceding equal-length period, not the same dates last year. Price-per-square-foot differences between primary and resale baskets are not evidence of a like-for-like discount or appreciation.
Ready property versus off-plan
New launches broaden the choice of design, specification and payment plans, while established homes offer immediate inspection and evidence of everyday community life. The investment comparison should test what the buyer gains from a newer product against the price and operating advantages of a ready alternative. Off-plan buyers should also assess delivery, handover funding and competing inventory.
The H1 resale subset contains 100 apartment and 19 villa transactions within the selected geography. These counts alone do not establish weak liquidity across wider Meydan: that requires available-stock, turnover and selling-time evidence. Ready status must still be checked per property because a resale can be an off-plan assignment.
The premium townhouse benchmark: Meraas’s Nad Al Sheba Gardens Phase 10 launch price sheet starts three-bedroom townhouses at AED 5.1 million, four-bedroom villas at AED 11.4 million and five-bedroom villas at AED 13.9 million, with estimated completion in February 2029. This supports the wider corridor’s premium positioning and a comparison with established homes. These are phase-specific launch prices, not current available inventory or a minimum for every upcoming project.
Rental, resale and operating economics
The supplied Rental views use contract Start Date, 1 January–30 June 2026, and the same Meydan, Nad Al Sheba First selection. The figures below are labelled average annual rent by DXBinteract, not medians.
| Property type | New contracts | New average annual rent (AED) | Renewals | Renewal average annual rent (AED) |
|---|---|---|---|---|
| Apartment | 351 | 100,000 | 417 | 95,000 |
| Villa | 36 | 319,600 | 24 | 310,600 |
These views contain 768 apartment and 60 villa contracts. New-contract average rents exceed renewal averages by approximately 5.3% for apartments and 2.9% for villas, but this is a comparison of different baskets, not a like-for-like rent increase. No occupancy rate is inferred from contract counts.
The platform displays rental yields of 7% for apartments and 6% for villas; their methodology and matched-property basis were not established, so they are not underwriting benchmarks. A decision-grade net yield must match annual rent to the unit’s acquisition costs, approved service charges, management, maintenance, vacancy and furnishing. Financing should be modelled separately for the buyer’s cash flow.
Before offer or reservation, use DLD’s Service Charge Index for the exact project and budget year and compare current Ejari evidence for the same building, bedroom count and furnishing status.
Project and micro-market comparison
| Route | Evidence to use | What to verify |
|---|---|---|
| Ready apartment | Same-building resales and Ejari contracts | Service charges, occupancy, parking, layout and building operations |
| Off-plan apartment | Registered same-project sales and delivery-stage peers | Escrow, construction progress, payment schedule, competing inventory and assignment rules |
| Villa or townhouse | Same phase, plot range and built-up area | Community maturity, landscaping, privacy, access, schools and family resale pool |
| Branded residence | Same brand, specification and service model | Brand agreement, recurring costs, rental restrictions and depth of ultra-prime buyers |
Where primary apartment activity is concentrated
The separate Most Sold panel uses its own YTD period: 1 January–4 September 2026, Apartment, Primary, Any Bed. Its 18 supplied rows total 1,644 transactions. The first five rows contribute 1,433 (87.2% of those listed transactions). Project names are retained separately; no parent-project grouping or H1 concentration is inferred.
| Project label | YTD transactions | Displayed price (AED) | Displayed AED/sq ft |
|---|---|---|---|
| Maybach Six – Tower B | 623 | 1.4m | 3,612 |
| Maybach Six – Tower A | 390 | 1.4m | 3,621 |
| Project Maybach | 192 | 1.4m | 3,555 |
| Maybach Ultimate Luxury – Tower B | 180 | 1.4m | 3,652 |
| Maybach Ultimate Luxury – Tower A | 48 | 2.3m | 3,798 |
The resale ranking for the same apartment YTD window is led by The Polo Residence – A3 (60), Azizi Gardens (5) and Prime Views (5). These are transaction counts, not unique units. Abnormally low D5 and C3 price rows are excluded from representative price examples. Published area totals have not been silently reduced or described as cleansed.
Historical context, with partial-year limits
The Trends panel did not change when the main property filter changed from Apartment to Villa. Its H1 monthly totals reconcile to the all-type summary, so these are not presented as apartment-only or villa-only trends. Prices below are rounded chart labels; the screenshot does not establish whether the yearly price statistic is a median or another measure.
| Year | Primary transactions | Resale transactions | Primary AED/sq ft, rounded | Resale AED/sq ft, rounded |
|---|---|---|---|---|
| 2022 | 142 | 201 | 1,200 | 1,200 |
| 2023 | 122 | 286 | 1,400 | 1,200 |
| 2024 | 337 | 315 | 1,400 | 1,400 |
| 2025 | 285 | 231 | 2,400 | 1,500 |
| 2026, partial | 1,693 | 140 | 3,600 | 1,600 |
Primary 2026 monthly counts include eight September transactions; resale monthly counts shown stop at August and sum to 140. The exact platform refresh timestamp is unavailable. These partial-year observations are not full-year growth comparisons, and changing project mix prevents interpreting the price series as same-property appreciation.
Micro-location, building and unit selection
- Confirm the DLD area, project number, developer entity and escrow account.
- Use same-project and same-unit-type registered comparables, separating primary from resale.
- Verify current service charges, building management, maintenance history and any hotel or brand fees.
- Inspect access, parking, layout efficiency, orientation, noise, views and future obstruction.
- Underwrite the likely tenant and resale buyer, then test a base and downside exit without relying on future infrastructure completion.
Who Meydan may suit
| Investor profile | Potential route | Main condition |
|---|---|---|
| Central-Dubai income investor | Operating apartment with matched rent evidence | Net yield survives service charges and vacancy |
| Long-horizon growth investor | Selective off-plan project | Entry price compensates for delivery and supply risk |
| Family owner-occupier | Ready or advanced villa community | Schools, retail, roads and recreation work today |
| Luxury buyer | Branded residence or premium villa | Specification, brand costs and resale depth are independently verified |
| Short-horizon investor | Selective only | Proven assignment/resale route independent of a future launch |
Catalysts and delivery timeline
- OperationalEstablished road access, occupied residential projects and the Meydan–Nad Al Sheba cycling connection.
- AwardedAl Meydan Street development: 17 km of roads, 3.7 km of bridges and cycling links under two awarded contracts.
- Future targetRTA states end-2028 completion for the Al Meydan Street programme; treat the date and travel-time benefits as targets until delivered.
- Approved — Metro Gold LineRTA’s 22 April 2026 announcement includes Meydan on the route and targets opening on 9 September 2032. Its stated procurement sequence is tendering in 2026 and contract award in 2027.
- Planned — Etihad Rail connectionThe same RTA announcement identifies integration with Etihad Rail at Meydan. A separate opening date and exact station-access arrangements for Meydan were not established in the reviewed sources; do not confuse this with the conventional passenger network’s 2026 rollout.
RTA’s Gold Line announcement provides a firmer basis for the connectivity thesis than an unconfirmed transport rumour. NYSA’s interpretation is that the planned interchange could widen Meydan’s accessibility and residential appeal over time. No uplift percentage or station walking distance is assumed.
Principal risks and what to verify
- Launch concentration: test whether the selected project’s resale audience exists beyond developer-led demand.
- Geography mismatch: confirm the DLD area and project rather than relying only on “Meydan” marketing.
- Delivery and specification: verify escrow, DLD project status, construction progress, contract remedies and handover funding.
- Operating-cost risk: use project-specific approved service charges and realistic maintenance/vacancy allowances.
- Liquidity risk: compare same-project resale counts and days-to-exit; do not infer liquidity from total area registrations.
- Infrastructure timing: underwrite the property on current access and treat future road benefits as upside rather than the base case.
Area decision summary
Meydan deserves serious consideration for buyers seeking central access without giving up a family-community setting. Gated developments, premium townhouse and villa launches, and approved future rail connectivity make a stronger case than the narrow transaction sample alone can express. NYSA sees an underappreciated central-living proposition here, particularly where an established home compares favourably with newer premium alternatives.
The next step is a matched comparison by community, plot, built-up area, specification and completion stage—not assuming that every Meydan property is a bargain. Buy for the location and residential proposition available now, with future road and rail investment adding a longer-term dimension.
For comparison, review Dubai Marina for a deeper ready-apartment market, Dubai Hills Estate for mature family-community positioning, and Dubai Silicon Oasis for a more value- and employment-led apartment market. You can also use NIA to define the investment brief before comparing projects.
Frequently asked questions
Is Meydan a good area for property investment in 2026?
Meydan offers a compelling combination of central access, gated family communities, premium housing and planned rail connectivity. NYSA views it as an underappreciated central-living proposition; investment suitability depends on the selected property’s entry price, specification, operating costs and holding period.
Is Meydan mainly an off-plan market?
The selected H1 2026 view contains 1,435 primary sales and 120 resales. That does not establish the ready/off-plan mix: primary and resale describe sales routes, while ready and off-plan describe construction status. Check the status of the individual project.
What rental yield can an investor expect in Meydan?
There is no verified single net yield for this guide. DXBinteract displays 7% for apartments and 6% for villas, but its matched-property basis was not established. Calculate the selected unit’s net yield using its rent, full acquisition costs, service charges, management, maintenance and vacancy.
Which DLD area should be used for Meydan comparables?
The supplied market views select Meydan, Nad Al Sheba First. They should not be treated as covering every project marketed as Meydan or MBR City. Confirm the exact DLD project and area before selecting comparables.
What should be checked before buying off-plan in Meydan?
Verify the developer entity, DLD project number, escrow account, construction progress, payment schedule, assignment rules, specification, service-charge assumptions, competing supply and a realistic resale or hold strategy.
Will Meydan have the Metro Gold Line and an Etihad Rail connection?
RTA’s April 2026 Gold Line announcement includes Meydan and planned integration with Etihad Rail there. The metro opening is targeted for 9 September 2032. A separate Meydan rail opening date and exact station-access arrangements were not established in the reviewed sources. These are future connectivity benefits, not operating services or guaranteed property-price gains.
Methodology and sources
Market figures are transcribed from owner-supplied DXBinteract screenshots received 3–4 September 2026, with selected periods and filters stated above. No direct DLD transaction extract is claimed. The earlier broker-report figures are superseded in this draft, not blended into the supplied data. Screenshots are the primary evidence for the displayed figures; the public link is a source landing page, not a saved filtered query.
- DXBinteract Meydan source landing page: owner-supplied H1 sales/rental views, separate YTD project rankings, and historical Trends screenshots.
- Dubai Land Department Real Estate Data: official transaction verification route.
- Government of Dubai Media Office / RTA, Al Meydan Street Development Project: contract award announcement dated 30 August 2026; target rather than delivered infrastructure.
- Dubai Land Department Service Charge Index: project- and budget-year-specific operating-cost checks.
- RTA, Metro Gold Line approval, 22 April 2026: planned Meydan route and Etihad Rail integration, procurement sequence and September 2032 target.
- Etihad Rail high-speed project: a separate future network; not evidence of an operating Meydan station.
- Nakheel’s District One location and Naya community information, Meraas’s Nad Al Sheba Gardens master-development page and Phase 10 price sheet are linked in the relevant sections; reviewed 4 September 2026. Developer travel estimates, specifications and launch prices are attributed rather than treated as completed outcomes or current inventory.
Build a property-level acquisition brief
NYSA can compare registered transactions, current project status, operating costs and realistic exit evidence for a shortlisted Meydan property.
Request an investment assessmentThis guide provides general market information and is not legal, tax, financial, investment or valuation advice. Verify the property, contract, costs, financing, project status and current UAE rules for the specific transaction.